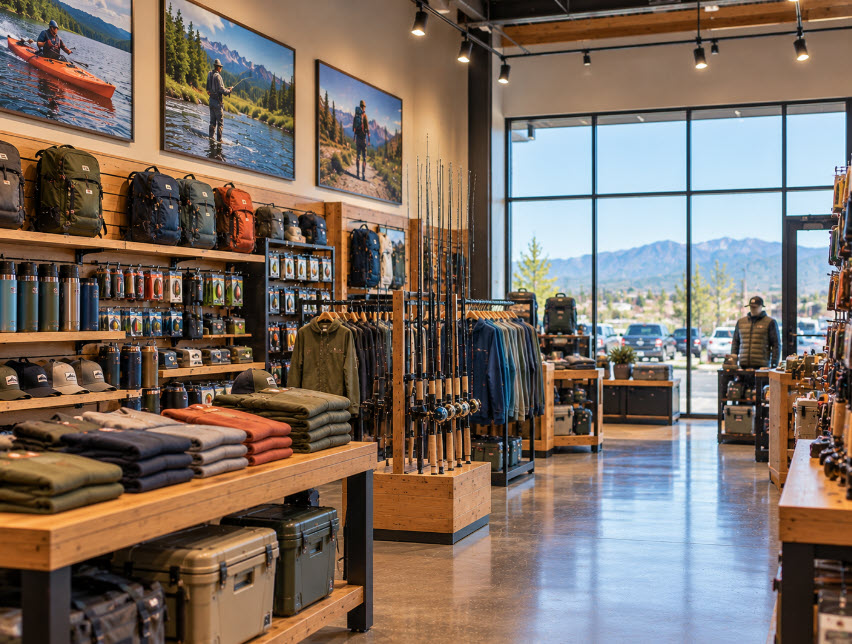
Sporting goods stores throughout Colorado sell athletic apparel, footwear, fitness equipment, fishing gear, camping supplies, bicycles and other outdoor recreation products. Some serve a broad range of customers, while others specialize in fly-fishing rods, reels, tackle, waders, hiking equipment or seasonal sporting goods.
Insurance needs depend on the merchandise sold, inventory values and services offered. Theft, customer injuries, product-related claims and property damage can create significant expenses, while stores offering rentals, repairs or equipment demonstrations may need additional protection.
How Much Does Sporting Goods Store Insurance Cost in Colorado?
In 2026, a smaller Colorado sporting goods store may budget approximately $1,500 to $5,000 per year for a commercial insurance program, although premiums can fall outside this range. A shop selling clothing, footwear and basic fishing tackle may cost less than a larger retailer carrying expensive bicycles, fishing electronics or specialized recreational equipment.
Businesses with substantial inventory, employees, equipment rentals or higher-risk merchandise may pay $5,000 to $10,000 or more annually. Revenue, payroll, inventory values, products sold, claims history and selected limits all affect pricing. These figures are planning estimates rather than verified Colorado industry averages.
What Insurance Does a Colorado Sporting Goods Store Need?
Many retailers can begin with a Business Owner’s Policy (BOP), which may combine general liability, commercial property and business income coverage. This can provide a foundation for customer injuries, covered inventory losses and temporary closures following certain property losses.
Additional coverage may be needed for product liability, employee injuries, theft, equipment rentals, repairs and merchandise transported between locations. The insurance program should reflect what the store actually sells and does rather than relying on a generic retail classification.
How Much Inventory Coverage Does a Sporting Goods Store Need?
Commercial property insurance can help protect eligible merchandise, shelving, displays, point-of-sale systems and tenant improvements against covered losses. Inventory limits should reflect replacement costs, including merchandise kept in stockrooms or other insured locations.
Seasonal inventory deserves particular attention. Fishing shops may carry more merchandise before spring and summer, while winter sports retailers often increase stock before ski season. Owners should review peak inventory values, theft protection, deductibles and any restrictions affecting expensive equipment.
Insurance for Fishing Tackle and Outdoor Equipment Stores
Fishing retailers may carry fly rods, spinning reels, tackle, waders, boots, fish finders, GPS devices and other specialty equipment. Higher-end rods, reels and electronics can represent substantial inventory values, making accurate property limits and theft protection important.
Stores offering rod repairs, fishing equipment rentals, casting demonstrations or guided outdoor activities should disclose those services when requesting insurance. These operations can create additional liability exposures beyond ordinary retail sales.
Does Sporting Goods Insurance Cover Product Liability?
Sporting goods are often used during activities where equipment failure can cause injury. Claims may involve allegedly defective helmets, bicycles, exercise products, protective equipment or other merchandise sold by the store.
Product liability insurance can help address certain bodily injury or property damage claims involving products sold or distributed by a business. Coverage may already be included in a general liability policy, but stores that import, modify or sell private-label merchandise should review product exclusions and underwriting requirements.
Are Equipment Rentals and Repairs Covered?
Sporting goods stores offering bicycle repairs, ski servicing, fishing equipment rentals or other recreational services can face liability exposures beyond ordinary retail sales. An injury involving rented or improperly repaired equipment may create a different type of claim than a straightforward merchandise purchase.
Owners should confirm that rentals, repairs and demonstrations are included in their insurance classification. Customer-owned equipment left for servicing, rental inventory and off-site activities may also require additional coverage.
What About Theft and Employee Dishonesty?
Sporting goods stores can be attractive theft targets, particularly when carrying expensive electronics, bicycles, footwear and other easily resold merchandise. Commercial property insurance may cover certain theft losses, but shoplifting, unexplained inventory shortages and employee theft can be treated differently.
Commercial crime insurance may provide additional protection for specified theft, employee dishonesty or fraud-related losses. Inventory controls, surveillance systems and appropriate security for high-value merchandise can also help reduce exposure.
Does a Sporting Goods Store Need General Liability Insurance?
General liability insurance can help address certain customer injury and third-party property damage claims. Heavy merchandise, equipment displays, demonstration areas and customers handling products before purchasing them can all create liability exposure.
Landlords may also require liability insurance before leasing retail space. Businesses offering equipment demonstrations or off-site events should make sure those activities are accurately disclosed and addressed by the policy.
What Happens if a Sporting Goods Store Has to Close?
A fire, major water loss or other covered property event can interrupt sales while rent, payroll and other expenses continue. Business income insurance may help replace lost income and certain continuing expenses during a qualifying shutdown.
Seasonal retailers should consider how a closure during peak fishing, camping or winter sports season could affect annual revenue. The time needed to repair the premises and replace inventory can be particularly important.
Do Colorado Sporting Goods Stores Need Workers Compensation?
Colorado employers with one or more full- or part-time employees generally must maintain workers compensation insurance, subject to limited exceptions. Retail employees may face injuries involving heavy merchandise, stocking shelves, moving equipment or performing repair services.
Premiums depend on payroll, employee duties and job classifications. Store owners should accurately describe retail, warehouse, repair and other employee responsibilities when requesting coverage.
What Do Insurance Companies Look at When Insuring Sporting Goods Stores?
Underwriters may review annual revenue, payroll, inventory values, merchandise categories, security measures and prior claims. Additional questions may involve rentals, repairs, online sales, private-label products and off-site activities.
Stores selling firearms, ammunition or other regulated products may require separate underwriting consideration. Specialized merchandise and activities should be disclosed accurately because they can affect coverage eligibility and exclusions.
Can Specialty Insurance Markets Help Sporting Goods Retailers?
Some sporting goods stores may not fit standard retail underwriting because of specialized merchandise, product liability concerns, equipment rentals or unusually high inventory values. Specialty commercial insurance markets may offer additional options depending on the business and underwriting eligibility.
Owners should review restrictions involving specific products, rentals, repairs, theft and property in transit before selecting a policy. Comparing coverage provisions is especially important when a substantial portion of the business involves specialized recreational equipment.
Find Insurance Coverage for Your Colorado Sporting Goods Store
Whether you operate a neighborhood sporting goods shop, fishing tackle store, outdoor equipment retailer or larger specialty sporting goods business, Castle Rock Insurance and its partners can help explore standard and specialty insurance markets based on your merchandise, property, liability and operations. Contact us today to request a Colorado sporting goods store insurance quote and review available coverage options.